Over the past few decades, natural disasters have become more frequent and severe and can happen with little warning. By preparing your finances ahead of time, you can help reduce stress, avoid losses and give yourself a better chance at a faster recovery. From building an emergency fund to protecting important documents and reviewing your insurance coverage, here are a few proactive steps that can make a significant difference when the unexpected occurs.
Build or refresh your emergency fund
According to the Federal Emergency Management Agency (FEMA) a healthy emergency fund for natural disasters should be a liquid savings reserve (a.k.a. cash you can pull out quickly) that covers between three and six months of essential expenses. Saving in general can be hard, but it’s especially important to focus on this financial goal before anything else if you live in an area affected by hurricanes, tornadoes, earthquakes or other natural disasters. If you’re starting from square one, don’t worry. You can follow these tips to start building your emergency fund today.
Start with a realistic goal
Not everyone can put away hundreds of dollars a month into savings, but saving something is better than having nothing at all. Even if it is only $5 a month, try to make a habit of “paying yourself first” every pay day by either transferring money immediately into your savings or setting up direct deposit through your employer.
Aim for three-to-six months of essential expenses
Depending on the nature of the emergency, it can take weeks to months to recover from the mental and financial impacts of natural disasters. Many survivors of extreme weather events can experience acute stress affecting their ability to work. Stress often peaks in the first month or two but can improve significantly by the three-to-six-month mark. Home repairs and community services like power, water and communications can take weeks to months to resolve, with delays in insurance claims commonly taking several months in major disasters. Having an emergency fund can help meet immediate needs and prevent accumulation of high-interest debt until things stabilize.
Where should emergency savings be kept?
One of the best places to keep an emergency savings is in a Money Market Account. These savings accounts earn higher dividend rates and annual percentage yields (APY) than regular ones. While the rates are typically higher for a Share Certificate (known as a “certificate of deposit” at banks), money market accounts allow you to access your money when you need it versus being locked up for a set term. Keeping your emergency fund in an accredited financial institution also means that it is federally insured up to $250,000.
Make sure you have the right insurance coverage for a disaster
Verify that you have the right insurance coverage in place for your home, vehicle and other possessions and understand what your policies do and don’t cover. Keep in mind that many policies don’t cover damage caused by weather that might be prevalent in your area, like flooding or fires, so you may need to purchase separate policies or endorsements for additional coverage. Below are some common insurances and ways to evaluate them to see what extra protection you may need.
Homeowners insurance
Typical policies cover 16 named perils including windstorms and hail, fire and wildfire, lightning strikes, winter storms and falling objects. You can check the “perils insured” and “exclusions” sections on your declarations page to see what the coverage limits are and if there are special deductibles for wind or hurricane damage (often 1% - 5% of dwelling coverage in Texas and coastal states).
Consider purchasing extra protection for:
- Floods
- Earthquakes
- Landslides and mudslides
- Sinkholes
Flood insurance
Since most home and renters insurance policies don’t cover floods, there are two different ways to ensure your home is covered in the event of a natural disaster.
National Flood Insurance Program (NFIP)
Administered by FEMA, this program is available in 22,600 participating communities and is delivered to the public by a network of more than 47 insurance companies. To explore policies and find more information about what’s covered, visit FloodSmart.gov.
Private flood insurance
If flood insurance coverage is not available to you through NFIP or you have a high-value home (greater than $250,000), you can shop around for a private policy. The tradeoff with purchasing a private policy is that while the coverage is more flexible with a higher limit, it can be less predictable on renewal, whereas the NFIP is stable and standardized.
Auto insurance
Liability-only policies will cover bodily injury and property damage you cause to others, but comprehensive coverage is the only type of auto insurance that will cover damage from a natural disaster. To make sure you have comprehensive coverage, check your declarations page to see if it is active and what the deductible is. If you live in an area with extreme seasonal weather, check your deductible before the season starts since most insurers will freeze plans once a storm is named or an emergency is declared. It’s also important to note that claims are typically settled at the actual cash value, not the replacement cost, so make sure you know how much your car is worth and adjust your deductible accordingly.
Life and disability insurance
Death from a natural disaster is usually covered under the “accident” category, but double check your policy for wording that excludes or limits “acts of nature” or “disaster.” If you are unsure, confirm in writing with your insurer that your policy will pay for disaster-related death, injury or disability and note any claim procedures or steps you’d need to follow.
Organize and protect your financial documents
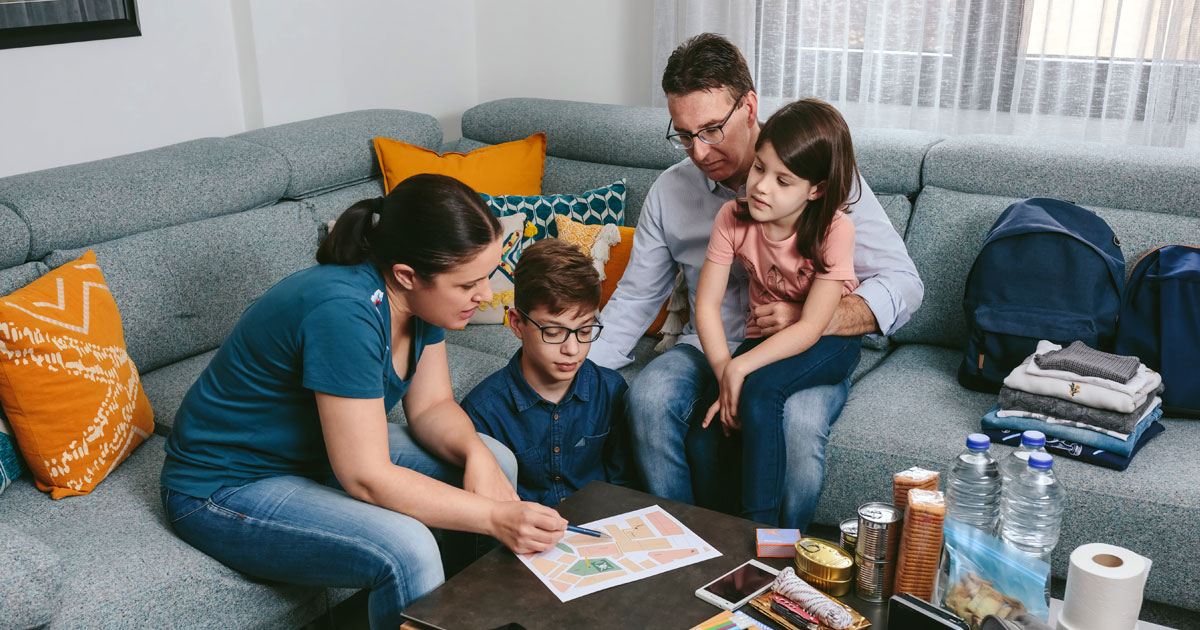
The Federal Trade Commission recommends preparing a “grab-and-go” kit with copies of your most critical personal, financial, legal and medical documents. Key documents to include are: your homeowners’ insurance policy, mortgage agreement, wills, deeds, estate plans, health care proxies, bank statements, birth certificates and passports. Consider keeping digital copies of everything, as well as a photos of your home and valuable personal belongings in case you need to file insurance claims.
Set up digital banking and autopay
The fewer financial concerns you have during an emergency, the better. By setting up digital banking and autopay, you can monitor and access your finances in the event a branch, ITM or ATM isn’t accessible. Benefits of managing your money digitally include:
- Access your accounts from anywhere: Digital banking lets you check balances, view transactions, transfer money and deposit checks using your phone, so that you can still access funds and manage bills when in-person services are disrupted by a natural disaster.
- Use automatic bill payments and direct deposit: Direct deposit ensures that your paycheck or other scheduled income is deposited to your account if you are unable to visit your financial institution. Autopay also prevents missed payments and helps cover urgent expenses without scrambling for cash.
- Transfer money when needed: Digital banking includes features like check deposit, Pay a Person and the ability to transfer money quickly from savings to checking accounts. These tools can help you quickly send money to loved ones, pay for urgent needs or access your emergency fund when physical access is difficult.
Have a financial recovery plan for immediately after a disaster
Once you’ve prepared for an emergency using the steps above, you can now shift to thinking about your recovery strategy. Below is a brief checklist to help you take action and recover quickly if you’ve been impacted by an emergency:
- Ensure your safety first: Follow all local emergency officials’ instructions and do not try to reenter damaged structures until it is declared safe.
- Contact your insurance provider: Notify your homeowners, renters, flood, auto and other relevant insurers as soon as possible and ask about emergency aid, deadlines and any required documents.
- Review available funds: Login to digital banking to review your balances, submit requests for support or fee waivers for disaster victims.
Additional resources for financial assistance and natural disasters
Financial preparedness won't prevent a natural disaster, but it can help you recover more quickly and with less stress. Taking small steps today, such as building savings, reviewing insurance coverage and protecting important documents, can strengthen your financial resilience when emergencies occur.
Some other great resources you can explore to make sure you are prepared include FEMA’s Individual Assistance Programs, state relief programs or you can talk with one of our Member Relationship Specialists to get connected to local programs in your area.